Friday, September 18 0.25% between the rate on the news and the rate on your sheet Freddie Mac published 6.95% yesterday morning. Lenders were quoting 7.20% today. The survey is taken Monday through Wednesday and released on Thursday, so the headline number is always a day or two behind the market. Your rate sheet is not. Freddie Mac PMMS and Mortgage News Daily, September 18, 2026. National averages for illustration only, not a commitment to lend. Your rate depends on credit, loan amount, property and full underwriting. |
|
Average rates today National averages, September 18, 2026 | Program | Rate | APR | | 30-Year Conforming | 7.20% | 7.31% APR | | 15-Year Fixed | 6.83% | 6.94% APR | | FHA 30-Year | 6.81% | 7.71% APR | | VA 30-Year | 6.82% | 7.07% APR | | Jumbo 30-Year | 7.36% | 7.47% APR |
HELOC, home equity loan and DSCR pricing is quoted per scenario, not as a national average, so there is no honest number to print here. Text me and I will quote yours. Conforming covers loans backed by Fannie Mae and Freddie Mac, which are not quoted separately. Sources: Mortgage News Daily daily averages and the Freddie Mac survey. APR estimates use industry-standard fee uplifts. National averages for illustration only, not a commitment to lend; your rate depends on credit, loan amount, property and full underwriting. |
|
From Debbie They raised it. On Wednesday the Fed lifted its target range a quarter point, to 3.75% to 4.00%, on a unanimous 12-0 vote. Not a cut. A hike. I have been telling you for three weeks that the market was pricing an increase while everybody else was waiting on relief. The statement said it plainly: inflation remains elevated, and the move supports a timelier return to their 2% goal. They also wrote that they will deliver price stability. Read that as a Fed that is not finished. Mortgage rates went with it. Freddie Mac’s survey jumped to 6.95%, nineteen basis points in a single week. Daily lender pricing is at 7.20%. And the 10-year Treasury, the number a 30-year mortgage actually tracks, touched 5.00%. We have not seen a five handle on that in a long time. So what do you do with that? Not panic, and not wait. Waiting has cost people money every single week this year. If you own a home, the equity you already have is worth looking at right now, which is exactly why I built the page below. — Debbie |
|
New on the site The HELOC page is live  HELOC vs. Home Equity Loan: Which One Fits You? If you bought or refinanced a few years ago you may be sitting on a low rate and a pile of equity at the same time. A line of credit lets you use the second without giving up the first. I walk through how a HELOC works and how it compares to a home equity loan. You can check what you qualify for in minutes. Pre-qualification uses a soft credit pull, so it does not affect your credit score, and it shows the rates and terms you actually qualify for. A hard pull only happens if you decide to continue and submit a full application. See the HELOC page |
|
This week’s buyer $450,000 · first-time · 680 score · $22,000 available $3,578 FHA 6.81% / 7.71% APR
$15,750 down · $203 MI
MI for the life of the loan | $3,691 Conventional 3% 7.20% / 7.31% APR
$13,500 down · $236 PMI
PMI drops off at 78% LTV |
A hundred and thirteen dollars a month apart, and not for the reason most people assume. FHA gets you in with a lower credit floor and easier debt-to-income guidelines, but that mortgage insurance follows you for the life of the loan. Conventional needs a stronger credit profile, and the PMI falls off on its own at 78% loan-to-value. Rates as of September 18, 2026 from Mortgage News Daily; APR estimates use industry-standard fee uplifts. For illustration only. Not a commitment to lend. Actual rates, payments and eligibility depend on full underwriting. Property tax estimated at ~1.0% of purchase price annually and homeowners insurance at ~$1,400/year; actual amounts vary by county, property and coverage. HOA dues not included. |
|
On the show this week 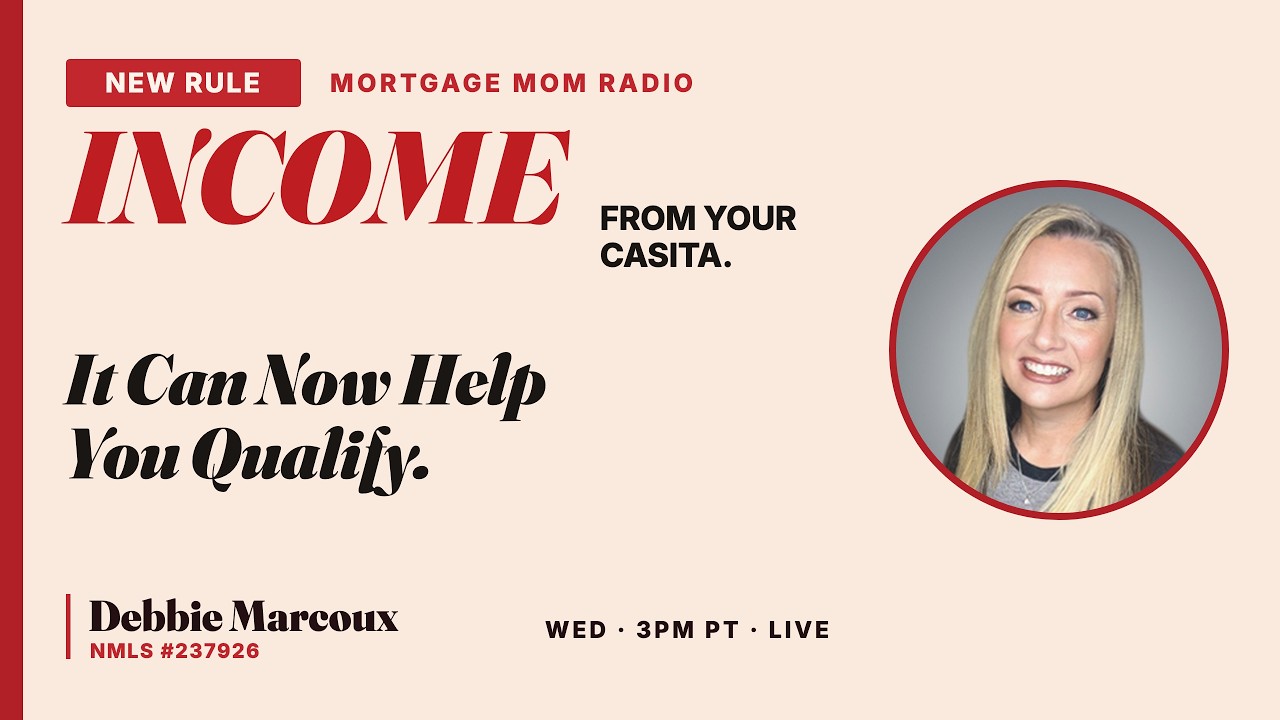 How Fannie Mae’s ADU Rule Helps Buyers Qualify Using Rental Income If you are looking at a home with a casita, a guest house or a converted garage, the rent from that unit may now help you qualify. Fannie Mae announced the change in October 2025 and it has been part of automated underwriting since March 2026. Debbie covers what counts as an accessory dwelling unit, who the rule applies to and who it does not, the limits on how much of that income can count, and why permitting and the appraisal matter. She opens with a two-minute read on Wednesday’s Fed decision. Watch the replay |
|
 | Talk to me Debbie Marcoux Mortgage Mom · NMLS #237926 · on air Wednesdays 3PM PT |
If something in here raised a question, ask me. You do not have to be ready to buy, you do not need paperwork, and there is no application involved. Most of what I do all day is answer questions for people who are still figuring it out. Pick a time that works for you and we will talk it through. Where I can help. Licensed in Arizona, California, Colorado, Florida, Georgia, Hawaii, Idaho, Illinois, Nevada, North Carolina, Oregon, Tennessee, Texas and Washington. If you are buying somewhere else, tell me anyway and I will say so straight away. |
|
|
Debbie Marcoux, NMLS #237926 · JMJ Financial dba Mortgage Mom Radio, NMLS #167867 · Equal Housing Lender. Licensed in AZ, CA, CO, FL, GA, HI, ID, IL, NV, NC, OR, TN, TX, WA. Debbie Marcoux is a licensed mortgage loan originator. She is not a financial advisor, investment adviser, tax professional or attorney, and nothing in this newsletter is financial, investment, tax or legal advice. Consult your own professional about your particular situation before acting. For illustrative and educational purposes only. Not a commitment to lend. Rates, terms and eligibility subject to underwriting approval and change without notice. |
|

