
What Can You Ask the Seller to Pay For? Seller Concessions in a Buyer's Market
Seller concessions hit a record 46.2% of home sales this spring, and the list price has become the opening bid. Debbie breaks down what buyers can ask a seller to pay for and why a seller-paid 2-1 buydown saves about $458 a month versus $71 from the same-size price cut.
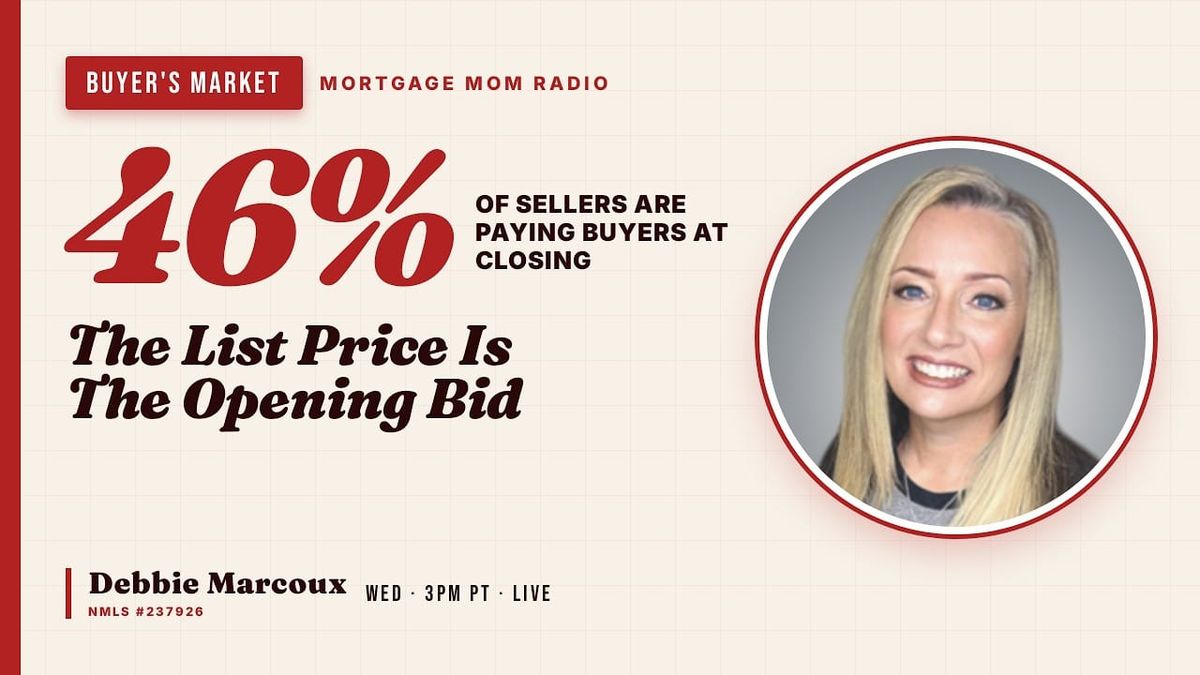
Nearly half of the people selling a home in America right now are handing the buyer money at closing — and most buyers still don't know they're allowed to ask. In this episode, Debbie walks through the data that makes 2026 officially a buyer's market, exactly what you can ask a seller to pay for, and why a seller-paid 2-1 rate buydown saves you far more money than the same-size price reduction.
Key takeaways
- Seller concessions hit a record. 46.2% of US home sales included a seller concession in May 2026 — up from 43.1% a year earlier and the highest share for any May on record (Redfin). That's regular resale homes; builder concessions run even higher.
- It's officially a buyer's market — and that's normal, not doom. There are 48.5% more sellers than buyers nationally, and inventory sits at 4.6 months. A normal market is four to six months — we haven't had this much inventory since before 2020.
- The list price is the opening bid. The typical resale home is closing at about 99% of asking before any credits, and 15.7% of May sales included both a price reduction and a concession. Getting one doesn't mean giving up the other.
- Concessions cover closing costs — never your down payment. Budget roughly 3% of the price for closing costs. The down payment must come from you or another acceptable source: a gift, down payment assistance, or liquidating a 401(k).
- The 2-1 buydown beats a price cut. On a $500,000 loan at 6.5%, the buydown costs the seller $11,379 and saves you about $458 a month over the first two years. The same $11,379 as a price reduction saves about $71 a month.
- Credits can stack. Seller, real estate agent, and even lender credits can all go toward the buydown — though a lender credit means taking a higher rate, so seller money is the money to chase.
- Sellers: a concession is a net-net. Giving a credit instead of cutting the price gets your home sold without becoming the lowest comp in the neighborhood.
Chapters
- 02:00Why 2026 is officially a buyer's market
- 03:00Nearly half of sellers are handing buyers money at closing
- 07:0046.2% of May sales included a concession (Redfin)
- 08:3048.5% more sellers than buyers — and 4.6 months of inventory
- 11:0015.7% of sales got both a price cut and a concession
- 12:30The 99% sale-to-list ratio; Arizona's routine concessions
- 15:00Where rates sit today, by loan type
- 17:00Why now: two years of inventory build while buyers waited
- 21:0057 days on market; one in five listings cut its price
- 26:00What you can actually ask a seller for
- 28:00A $500K example: down payment vs. closing costs
- 30:00The 2-1 buydown, explained
- 36:00The math: buydown vs. price reduction ($458 vs. $71 a month)
- 41:00Q&A: asking for the buydown after your offer is accepted
- 46:00State by state: Arizona, California, Florida, Nashville, Oahu
- 57:00The take-home: ask for the credit, aim it at the rate
Questions answered on this show
“Can you ask the seller for a rate buydown after your offer is accepted — for example, using a repair credit?”
Yes. A repair credit is still a seller concession, and it doesn't have to be earmarked in the contract for a specific use — the credit can be applied toward a buydown. The catch is size: repair credits usually come in around $4,000–$5,000, which isn't enough for a 2-1 buydown on a $500,000 loan, but it is enough for a one-year buydown — year one at 5.5% instead of 6.5%, then 6.5% for years two through thirty. The cost of any buydown depends on your exact loan amount and rate, so talk to your lender before you write the offer so you ask for the right dollar amount.
“Can the buydown funds come from multiple sources — the seller and the real estate agent?”
Absolutely. Seller and agent credits can combine toward the same buydown, and many of the agents Debbie refers clients to will credit what would have been a referral fee toward the buyer's closing costs. A lender can contribute too, but there's a trade: to hand back a credit (say $5,000 on a $500,000 loan — one full point), the lender has to price your loan at least a quarter percent above market, so most people prefer to start at the lowest rate and let the seller's money do the work.
This week's numbers (week of August 19, 2026 — averages, not quotes)
- Conforming 30-year conventional: ~6.625%
- High-balance conventional (common in California): high 6s to low 7s
- Jumbo interest-only and non-QM (bank statement, DSCR): mid 7s — roughly 7.25–7.5%
- FHA and VA: ~6.25%
- Share of May 2026 sales with a seller concession: 46.2% (Redfin — a record for any May)
- Months of inventory nationally: 4.6 (normal is 4–6); median listing sat 57 days in July
- Homeowner equity nationwide: $18 trillion, a record
Your rate depends on FICO score, property type, loan balance, and loan purpose. These are national conforming averages for context, not a quote.
Plan your offer — and your concession ask — before you write it
Call 844-935-3634 (844-WE-LEND-4), start an application, or run your numbers with the mortgage calculators. Get the weekly rate rundown in the newsletter.
Full transcript (lightly edited for clarity)
Auto-generated captions cleaned for readability. Sponsor messages, commercial breaks, and repeated housekeeping have been trimmed; licensing information appears at the bottom of this page. This episode was sponsored by Vera Nelson of Hythe Realty, Pasadena.
It's officially a buyer's market
Welcome to Mortgage Mom Radio. I'm Debbie Marcoux, the Mortgage Mom. It is Wednesday, August 19, and today we're talking about why this has officially become a buyer's market — what the data behind that statement is, and what you can do as a buyer to capitalize on it.
Here's the headline: nearly half of the people selling an existing home in America right now are handing the buyer money at closing — closing costs, repair credits, rate buydowns — and the buyers who don't get those simply aren't asking.
Now, I'm going to have people jump into the feed and tell me, “There's no way — I paid over list price and there were multiple offers.” Remember, this podcast goes across the nation. There are definitely areas, including pockets of California, still seeing multiple offers over list. But those are pockets — and they're not even everywhere in California. On average across the country, we are seeing closing cost credits and rate buydowns, and honestly, that's great for sellers too. I would much rather see a seller get their price and give credits than reduce their price and become the lowest sale in the neighborhood, driving the market down.
The numbers behind it
Let's jump into the numbers, because they back up my statement that the listing price is just the starting point. Even if you pay full price for the home, it is okay to ask for the things you need.
46.2% — the share of US home sales where the seller gave the buyer a concession in May of 2026. That's up from 43.1% a year earlier and the highest share for any May on record, according to Redfin. I always tell you where I find my data so you can double-check me. And that's regular homeowners selling regular resale homes — builder and new-construction numbers are actually quite a bit higher. I focused this show on resales because that's the majority of the activity in the market and the majority of what crosses my desk.
48.5% — how many more sellers than buyers there are in the market nationally right now. That's the leverage behind every one of these credits.
Now, a lot of people hear “buyer's market” and jump straight to recession, prices dropping, doom and gloom. That is not the case. A buyer's market just means there's more inventory than buyers. We're running at about 4.6 months of inventory, and a normal market is between four and six months. We have not had this much inventory since before 2020 — COVID took us to the lowest inventory we've ever seen, which is why houses were getting 10, 12, 20 offers. That is not the case now. We're a buyer's market, but we're in a normal inventory market. The headlines could very easily spin this into something negative when it's just the facts.
15.7% — the share of home sales that included both a price reduction and a concession, per Redfin. Getting one does not mean giving up the other.
99% — the average sale-to-list ratio right now, per Redfin's weekly data through mid-August. The typical resale home is already closing about 1% under asking before any credits. You don't necessarily have to offer list price — though if it's a hot home priced aggressively to drive bids, lean on your real estate agent to guide the offer.
And in Arizona, buyers are routinely negotiating 2 to 3% in seller concessions right now — $8,500 to $12,750 on a typical home, per the Arizona Daily Independent.
Where rates are today
Since about mid-July, interest rates have moved up and buyers are feeling squeezed again. Depending on the loan product: if you're in a bank statement loan, a DSCR loan, or a jumbo looking for interest-only, you could easily be in the mid-sevens — 7.25, 7.5. Conventional high-balance — which is a lot of California — high sixes to low sevens. A normal conforming conventional loan is still about 6.625 today, and VA and FHA are running around 6.25. With rates higher, buyers have stalled, and properties going under contract have absolutely slowed over the last couple of weeks. Sellers: if you want your home sold, be open to helping the buyer buy down that rate — that's how your home goes under contract while your neighbor's listing sits.
Why this is happening now
Inventory has been building for two years while buyers sat out waiting on rates. The normal turnover of the market — downsizing, upsizing, families growing — hasn't been happening for years because people are locked into very low rates. I have a client right now doing a home equity line specifically because they don't want to touch their 2.65% fixed mortgage.
The other thing that stalled people was sticker shock. I hate to be the one to tell you, but that ship has sailed: rates have been above 6% since 2023. In late 2023 and early 2024 we were at 7.5 to 8%. We came down in 2025 and hit the high fives, which was phenomenal — and then 2026 took us right back up to the mid-sixes and low sevens. A lot of buyers waiting for threes and fours finally realized they're not coming back, but they missed the boat on the high fives — and the people who never got off the sidelines also missed lower prices, because values are higher today than they were in 2023 and 2024.
Which just proves what I've said all these years: you cannot time the market. If it's your time to sell, sell. If it's your time to buy, buy. The only thing I ask is that you get into something you can afford assuming you never get the opportunity to refinance. Then, when rates do drop — like they did in late 2025, when we were calling clients to cut a full point off their rate — take advantage of it. On a $500,000 or $600,000 mortgage, that's three, four, five hundred dollars a month.
A few more data points: the median listing sat 57 days in July — the slowest July pace in years — and one in five active listings took a price cut in July, per Realtor.com. This is a negotiation, not a fire sale. Sellers are not desperate: quite a few are simply pulling their homes off the market rather than cutting price, because they're sitting on great rates and record equity. Homeowners nationwide are sitting on $18 trillion in equity right now.
What you can ask a seller to pay for
A closing cost credit — most commonly called a concession — is the seller giving you a credit through the closing of the loan. One rule up front: the seller's concession cannot cover any of your down payment. The down payment has to come from you or another acceptable source — down payment assistance, a gift from a family member, liquidating a 401(k).
Then you have closing costs. Every state is a little different — Texas runs more expensive than California as a percentage — but on average, closing costs run between 1.5 and 3% of your sales price. Budget for 3% and you'll likely come in under.
So say you're buying a $500,000 home with 5% down. Your down payment is $25,000, and closing costs at 3% are roughly $15,000 — you need $40,000 to close. If you've only got $30,000, you have the down payment but not the closing costs. The seller can give you a $15,000 concession to cover those closing costs — and now you've actually got $5,000 left over to help with the move. Moving is expensive; think about what it cost just to fill your refrigerator and pantry last time.
The 2-1 buydown: my favorite program
Where the seller's money helps even more is a buydown. Don't confuse a buydown with points. A permanent buydown lowers your rate for the whole 30 years — say 6.5% bought down to 6.25% — and yes, a seller can pay for that. But my favorite is the 2-1 buydown, because it gives you the biggest savings in the first two years, much larger than a permanent buydown — with the hope that rates improve in the meantime so you can refinance if you want to. And this is nothing like the loans that got people in trouble years ago: a 2-1 buydown is a 30-year fixed loan. The note rate never changes. The seller just prepays the difference so your payment is based on a rate 2% lower in year one and 1% lower in year two. If rates never drop, no big deal — in year three you're simply at the rate you would have started at today.
Let me run real numbers — averages, for educational purposes only, not a quote. Take a $500,000 loan at 6.5%. Year one, your payment is based on 4.5% — that's a savings of $626.91 a month, or $7,522 for the year. Year two, your payment is based on 5.5% — $321.39 a month, or $3,856. Over two years you keep $11,379 in your pocket — and that's exactly what the buydown costs the seller. When you negotiate, you ask the seller to pay for the buydown and you write the specific dollar amount into the offer. The number depends on your loan amount and rate, so call me before you write the offer and we'll calculate exactly what to ask for.
Now compare that to a price reduction of the same size. Knock $11,379 off the price instead, and your loan amount drops to about $488,621. At 6.5%, the payment on the full loan amount is about $3,160 a month; on the reduced loan amount, about $3,088 — you save roughly $71 a month. The buydown, spread over the same two years, saves you about $458 a month. That's why I love this program: $458 versus $71, from the same seller dollars.
And you're not limited to one source. The seller, the real estate agent, and even the lender can contribute — though when a lender gives a credit, we have to price the loan above market to create it. To hand back $5,000 on a $500,000 loan — one full point — I'd have to raise the rate at least a quarter percent, to 6.75 or even 6.875. That's why most people let the seller's money do the work and keep the lowest start rate. Many of the agents I refer clients to will also put what would have been a referral fee — which I don't want and legally can't accept as a loan officer — toward your closing costs instead. Between an agent credit and a seller credit, you might walk in the door with just your down payment.
State by state: where the leverage is
Arizona is firmly a buyer's market. The median sales price statewide is $443,611, nearly a third of Phoenix-metro listings have taken a price cut, and 2–3% concessions are routine — I've been seeing them on almost every contract that comes through in Tempe and Chandler.
One thing buyers should understand about what a seller is actually giving: if you buy at $600,000 and ask for 3%, that's an $18,000 concession — the seller really agreed to net $582,000. It's a direct net reduction for them, and you're ultimately getting the home at a lower effective value — while the neighborhood's comps stay strong. That's why concessions beat price cuts for everyone.
California sales are up 6% year-over-year, but the median price has eased 2.8% off May's record — and the median price is brutal for first-time buyers. If you're a California seller, be open to concessions. I've had buyers offer full price, even above asking, to get credits for what they need in cash — and sellers turn up their noses like it hurts them. It's a net-net, guys. If the buyer offers $10,000 over list to get a $10,000 credit, you're netting the same. Help them out. And remember what changed with agent commissions after the National Association of Realtors settlement: buyers are barely scraping together down payment and closing costs. When you bought your home, the seller paid your agent's commission. If a buyer asks you to cover their agent's commission or closing costs, counter on price if you need to protect your net — but help them get in the door.
Florida values have fallen three straight months, down 2.4% year-over-year, with roughly a quarter of listings carrying price cuts — among the most concession-friendly resale markets in the country. I've done four or five Florida loans in the last twelve months, and just about every contract I see has the seller offering fairly decent concessions. Florida also has some amazing down payment assistance programs.
The national extreme is Nashville, where 75.5% of sellers gave concessions in May — three out of four, the highest of the 28 metros tracked. Nashville, like Texas, got run up artificially during the pandemic and is now price-correcting, which is okay — it needs to. And if you bought there and you're slightly underwater: this is not a walk-away-and-ruin-your-credit scenario. The declines are small. Hold on. Real estate always comes back in every cycle, and every cycle tops higher than the last.
On the flip side, Oahu is hot — resales up 20.5% in July with the median up 13.9%, per the Honolulu Star-Advertiser. The leverage is local: days on market and price-cut share on the specific listing tell you how hard to push. There are pockets that are great and pockets that are not. This is a very normal market — honestly the most normal we've seen since 2019.
The take-home
The list price is the opening bid. Ask for the credit, and aim it at the rate: buy the rate down, get the monthly payment lower, ask for closing costs to be covered, and get in with the money you have in your pocket. Stop putting your plans on hold trying to time your way back to 3 and 4% rates — those aren't coming back short of another once-in-a-generation event. Will rates dip into the fives someday? I believe so, and if you buy today you'll have the opportunity to refinance. But this is the new average, so make sure the payment you sign up for is comfortable.
If you want to talk through your scenario, go to mortgagemomradio.com and book an appointment on my calendar — we'll go over your goals, your credit, and your down payment, get you pre-approved, decide what to ask the seller for before you shop, and hand you off to an agent we trust. You can also call the office at 844-935-3634, and if you want to know when I go live, text the word LIVE to that same number. Subscribe to the weekly newsletter on the website for rates, side-by-side comparisons, and links to every show. I'll be back next Wednesday right around 3:00. Talk to you all real soon.
Debbie Marcoux is licensed by the Department of Financial Protection and Innovation under the California Residential Mortgage Lending Act, NMLS ID #237926, and additionally licensed in AZ (0941504), FL, GA, HI, ID, IL, NV, NC, OR, TN, TX, and WA. Rates and figures discussed were current as of the air date of August 19, 2026, reflect national conforming averages, and are not an offer of credit or a rate quote. Debbie Marcoux is not a financial advisor; consult qualified professionals about your individual situation.
More episodes like this
How Do You Assume Someone Else's 3% FHA Or VA Mortgage?
Sellers holding 2020-2022 rates can sometimes let a buyer take the loan over. Debbie explains which loans are actually assumable, why you still qualify from scratch, how to cover the cash gap between the balance and the price, what a VA seller gives up, and how long it really takes.…
What Actually Moves Mortgage Rates? (It's Not the Fed)
The Fed hasn't moved once in 2026, yet mortgage rates are up sharply. Debbie explains the 10-year Treasury, the August 17 global bond sell-off, and whether to lock before Jackson Hole.…
Are Foreclosures Rising in 2026? Why This Is Not 2008 All Over Again
Foreclosure filings are up 21% year-over-year and the headlines are screaming 2008. Debbie puts the real numbers side by side — the 2010 peak, the normal market of 2019, and today — and shows why record equity and ability-to-repay underwriting make this a normalizing market, not a crisis.…